Long Treasuries (TLT): Exhausted Sellers, Capped Rallies
How AI borrowing crowds the Treasury market, why exhausted bond bears leave TLT range-bound, and what that means for options premium.
Anything but bonds
The long end of the Treasury market has become the asset nobody wants to be seen holding. The long bond yields more than at any point since 2007, trend followers are as short as their models allow, and the floors have an acronym for the mood: Anything But Bonds. I treat that kind of unanimity as information. When everyone who wanted out is already out, the next seller is hard to find, and the price stops falling for lack of ammunition.
What stops the stall turning into a rally is the other side of the same ledger. Every bounce in TLT runs into a wall of fresh supply, with the fear of Japanese buyers stepping back sitting on top. Soft labour data puts a floor under the thing; relentless issuance puts a lid on it. The letter's conclusion: the long bond drifts sideways while both camps catch their breath, and indecision, rather than direction, is where the money sits.
AI paper crowds out Washington
The supply side explains why the lid is so heavy. Corporate borrowing is running far ahead of last year, and AI-related companies alone have raised around $269 billion so far in the year, many multiples of what a normal year used to bring. All of it competes with the Treasury for the same pool of duration buyers. The curve steepens structurally, long-dated demand gets crowded out, and a quiet suspicion spreads that nobody really steers long yields anymore.
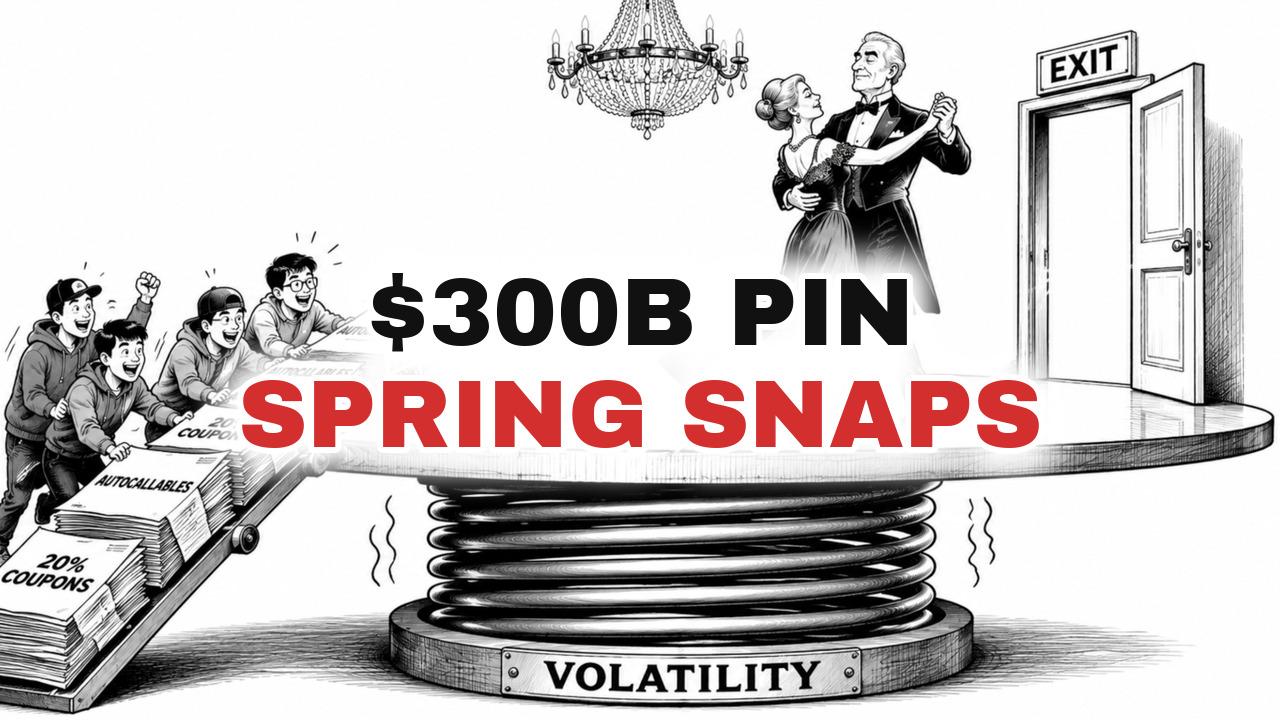
The rest of the tape is stranger still. Equity volatility sits at yearly lows because Korean retail investors, freshly returned from swearing off stocks, are funding fat coupons by writing autocallable notes on Nvidia, Micron and Tesla; dealers hedge those notes by shorting volatility, and the whole market gets pinned. Jane Street, built to ignite momentum and skim the spread, just broke a decade-long run of profitable months on its own reflexes. And the Rothschilds' Monaco bank calls AI a probable bubble while advising clients to own the shovel-makers and watch credit for the exit. Calm on the surface, coiled underneath.
Collecting rent on a stalemate
For an options trader this changes the question entirely. A directional bet on TLT needs bonds to do something, and the thesis is that they do nothing much. What passes in a stalemate is time, and time is what an options position can be paid for. The letter's shape is an iron condor: a defined range, premium collected on both wings, and a daily drip of theta while both camps argue. The full structure stays behind the button.
The risk is written into the same setup. Pinned markets, whether by Korean notes or by exhausted bond bears, grind quietly and then gap, and history says the crowd ends up chasing. A range structure earns while the range holds and demands discipline the moment it stops. It also sits comfortably beside the letter's equity stance: with index protection priced at pocket change as the hostile stretch of a midterm year begins, hedging and premium collection can share an account.
Minutes, an auction, then Warsh
The calendar is thin but pointed. Wednesday brings the FOMC minutes, which will show whether the hawkish appetite spread beyond July's dissenters. The same day carries the long-dated Treasury auction the letter flags as potentially the most expensive issuance in decades; the tail on that sale says more about the lid on TLT than any speech. Home Depot, Target and Walmart test the softening consumer, Friday's flash PMIs round off the calendar, and Jackson Hole on August 28 is where Warsh finally shows his cards.
Beyond the dates, I watch gold holding its reclaimed ground, since bullion wins whether the fear is inflation or deflation, and crude breaking the range Washington has kept it in by firing contradictory headlines daily. Either would tell me the spring is unwinding. Until then, the long bond's most likely act is to do nothing, loudly, and there is a way to be paid for watching.
Get the next Tuesday Target free
One real options trade every Tuesday before the US open, entry, stop and target named. Free to read.