Portfolio Update: The Currents Holding a Nervous Market Up
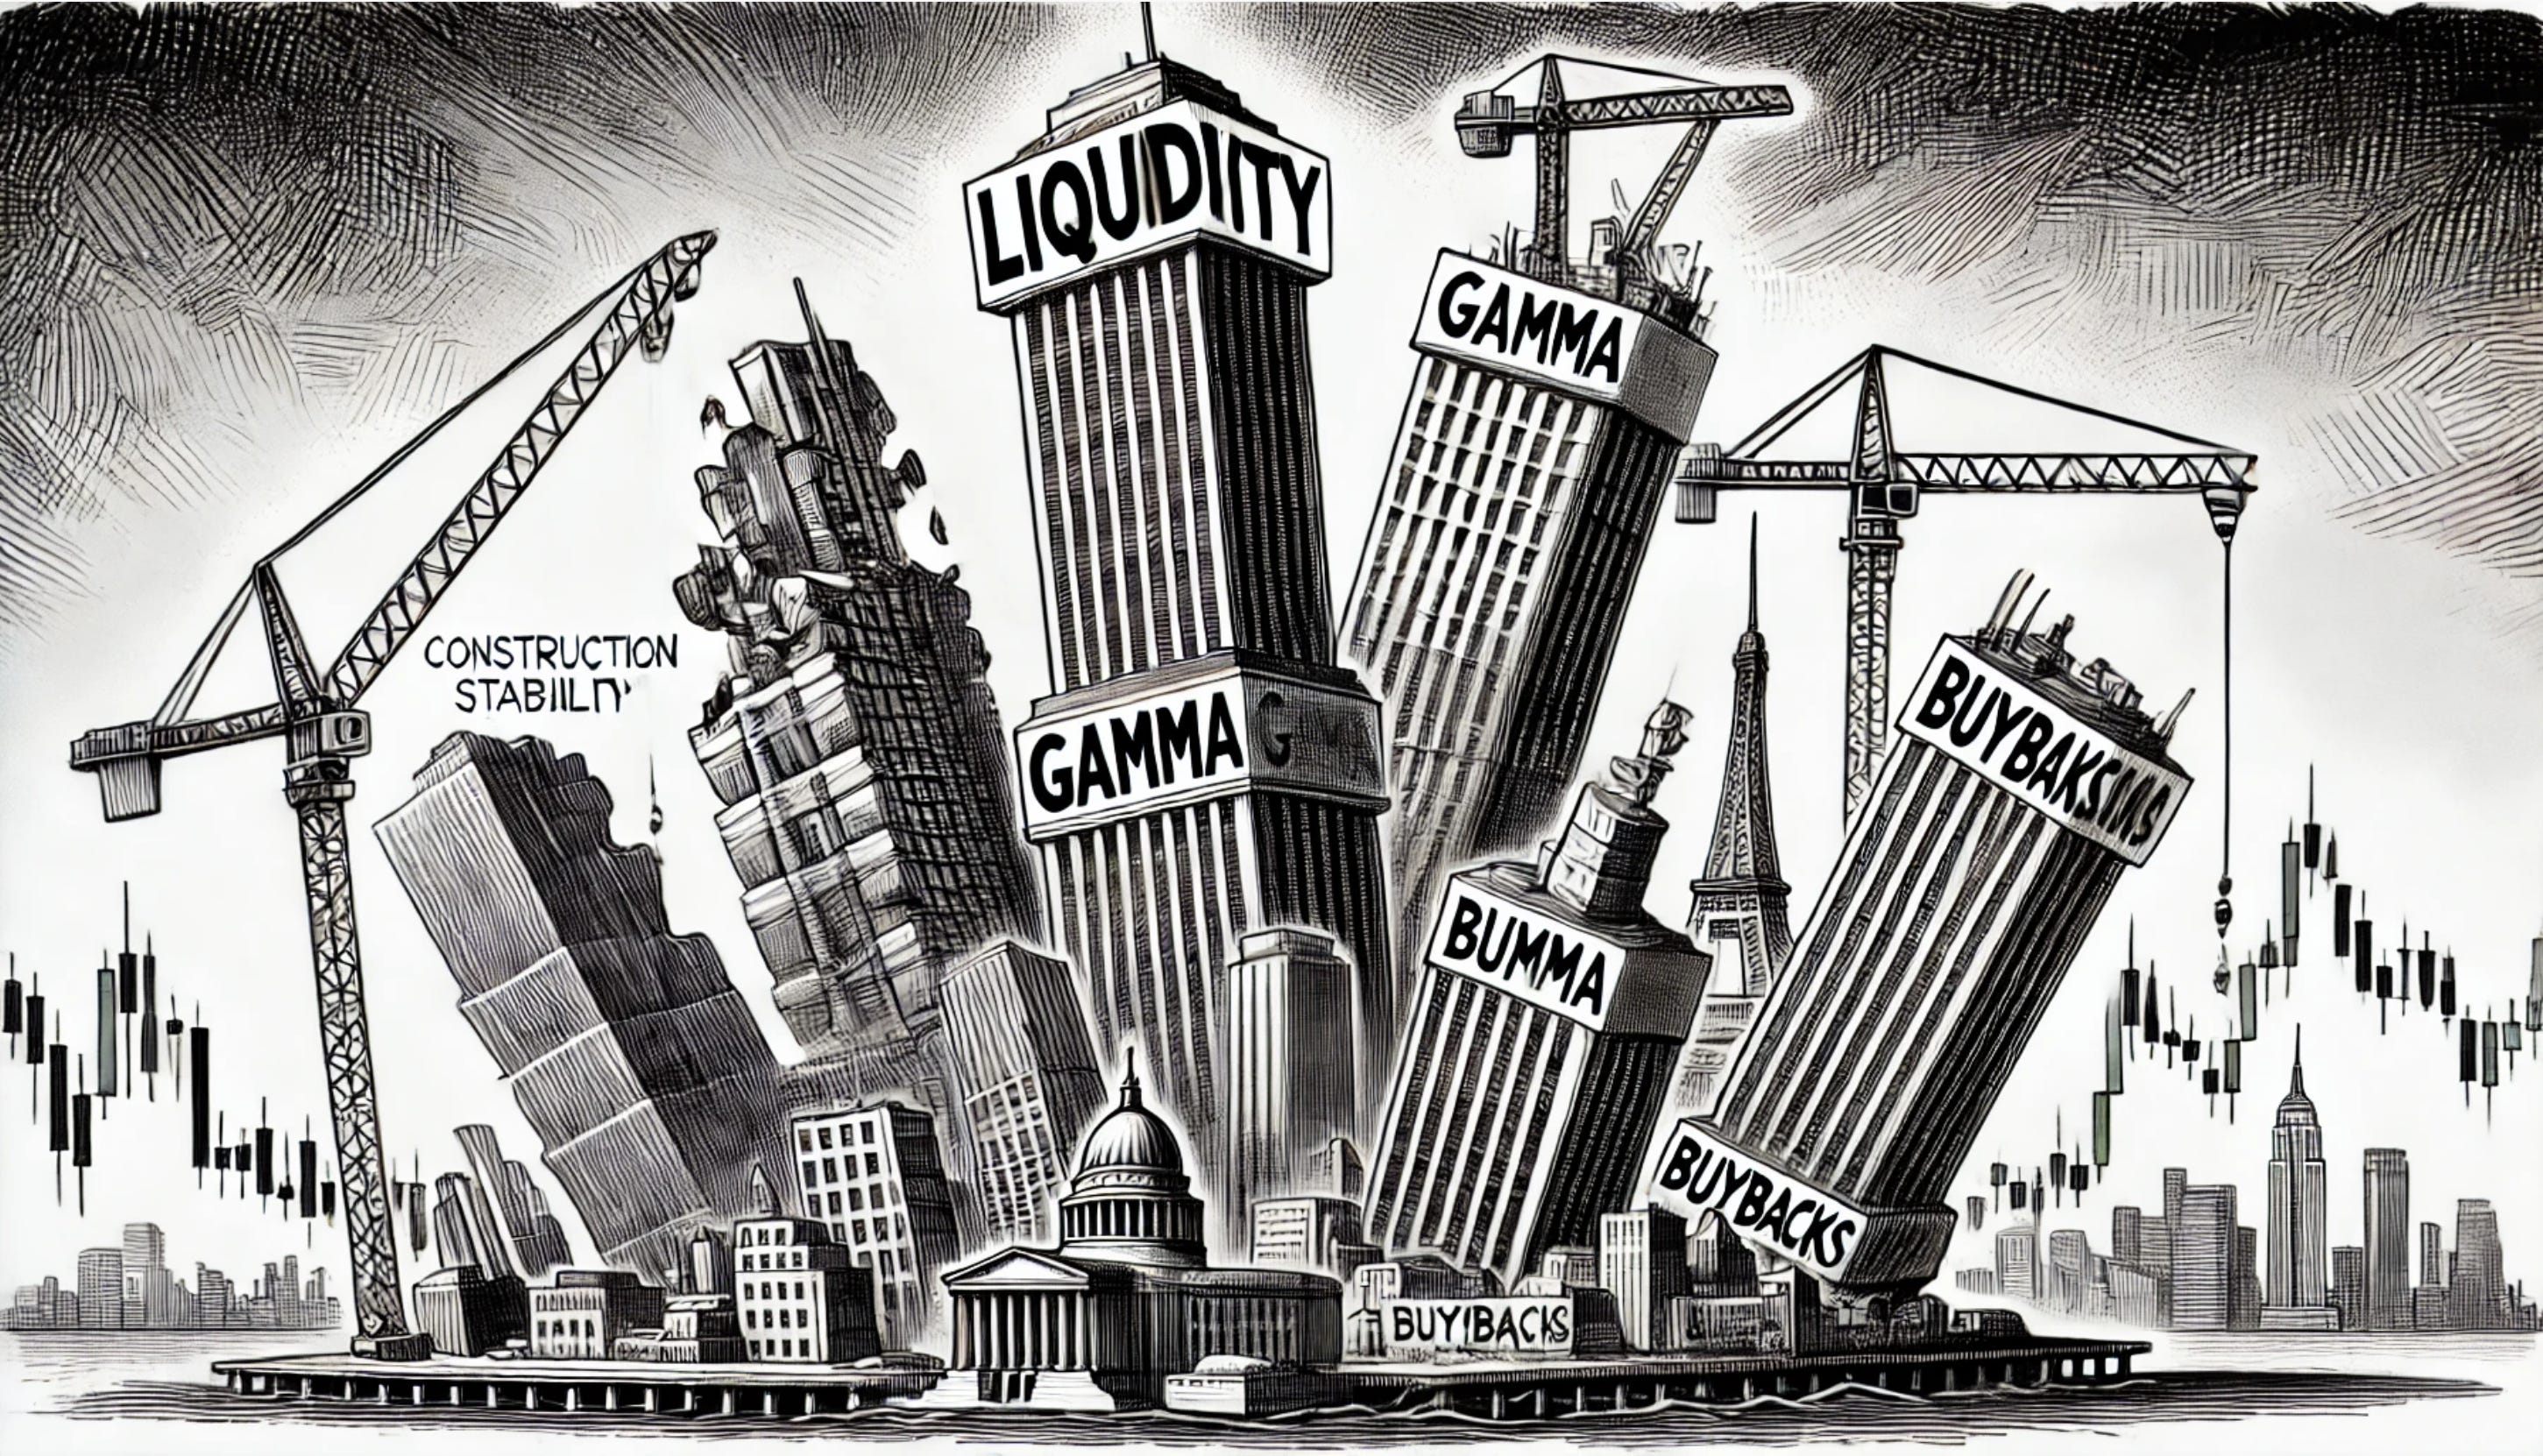
Why Fed liquidity, negative gamma and a wide-open buyback window explain a market that shakes hard but refuses to sink.
Liquidity Below the Waterline
Most market commentary describes the waves. The letter went looking for the water underneath them, and found the Federal Reserve quietly adding liquidity while everyone else argued about whether the recession had started or the correction was over. That is the part I wanted to step back from. Liquidity behaves like buoyancy: nobody thanks it while the ship floats, and everybody discovers it the moment it drains. Stocks held together through a rough patch because there was more cash in the system to catch the falls, and for no more flattering reason than that.
The sardonic version is that a central bank plumbing job never makes the front page, so the market gets credited with resilience it did not earn. I prefer the plumbing explanation. It is cheaper than a narrative and it tells you what to fear: the day the tap tightens rather than the day a strategist changes a price target.
Greedy Gamma, Bigger Waves
The second current runs against the first. Dealer gamma has slipped into negative territory, and in that regime the people hedging the option book have to lean into every move, selling as prices fall and buying as they climb. Negative gamma holds no opinion about direction. It simply turns the volume up on whichever way the market was already going, so both the drops and the rebounds arrive sharper than the news would justify.
For anyone holding options this is the part that matters most, because gamma is the mechanism that decides whether a position feels calm or feels like a rodeo. In a negative gamma tape implied volatility stays bid, both tails fatten, and short-dated positions swing further than their deltas would imply. It also punishes anyone who mistakes a violent rally for a trend. A bounce in this regime is dealers covering, and it can reverse with the same enthusiasm. The letter's only trade line fits the picture: the existing positions are all recovering hard towards their maximum profit, with the specifics left in the Subscriber Chat. Amplification cuts both ways, and the letter caught it on the friendlier side.
Buybacks Row the Other Way
The third current is corporate. With over 90% of companies inside their buyback window, the treasurers are back in the market, and their bid has a useful quality: it does not read the headlines. Repurchases arrive on schedule, on weak days as readily as strong ones, which makes them exactly the sort of price-insensitive buyer that negative gamma otherwise lacks. Stack them on top of the Fed's liquidity and the steady flows outnumber the jittery one. The letter's conclusion is that this combination may be enough to blunt the volatility and lay the groundwork for a rebound, and I would only add that the buyback window closes on a calendar, so the support has an expiry even if nobody prints it.
So the things to keep an eye on are the signs on each current rather than any single print. Whether the Fed keeps easing conditions or lets them tighten. Whether gamma flips back to positive, which would calm the swings and remove the fuel behind fast recoveries as well as fast drops. How long the buyback window stays open and how the recession and correction chatter evolves once it shuts. And the honest reminder buried in the letter's own subheading, that nobody gets rich overnight with options. Positions recover because the currents turned, and the same currents turn back. The job is knowing which way the water is moving before deciding how far to swim.
Get the next Tuesday Target free
One real options trade every Tuesday before the US open, entry, stop and target named. Free to read.