S&P 500 (SPY): Renting the Nap Before the Reload
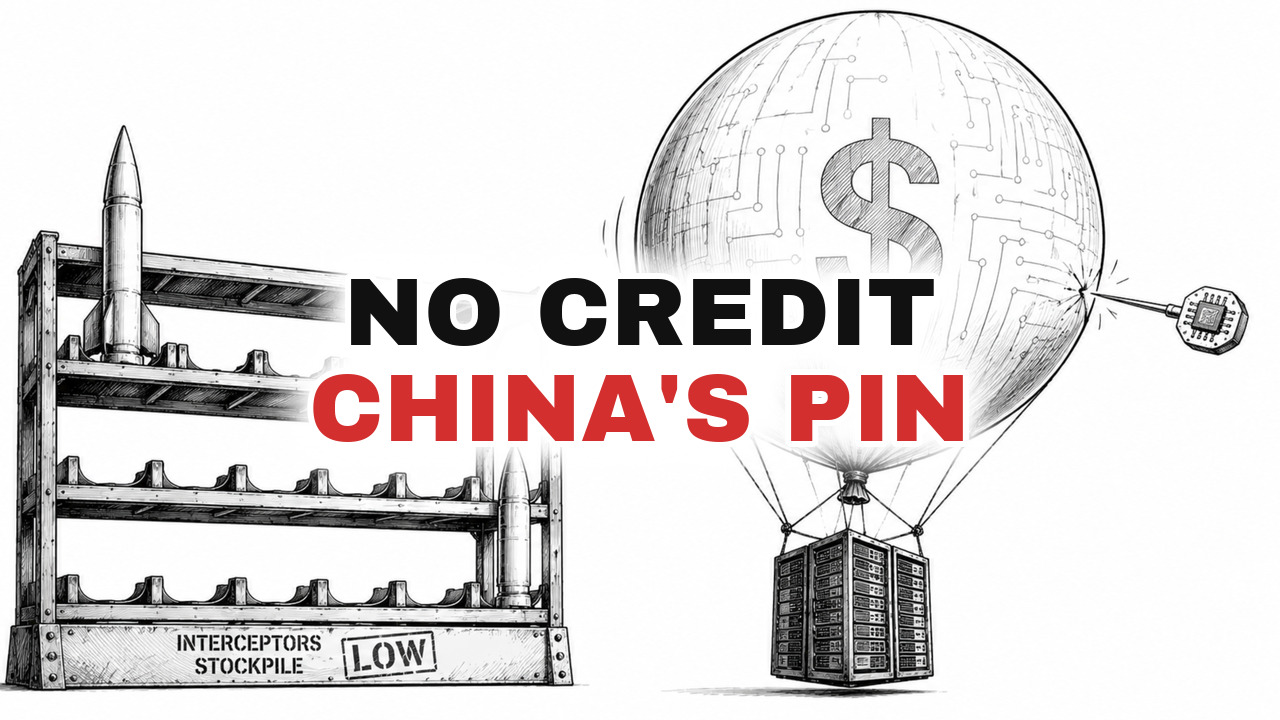
SPY and why the Gulf strike pause, AI debt and a coin-toss Fed leave index volatility cheap ahead of the midterm chop.
Peace When the Racks Run Low
Start with the Gulf. After the better part of a fortnight of strikes, Washington remembered it employs diplomats, and the timing was exquisite: leaks about the Pentagon's interceptor inventory wearing thin, the far end of the Treasury curve groaning. Crude sank, equities breathed out, the commentariat awarded medals for statesmanship. I read it as a pause to restock. Presidents talk peace when the launchers sit empty and the portfolios bleed.
Wall Street runs its own campaign, the AI buildout, and its ammunition is credit. Fresh AI borrowing this year has reached a scale that makes lenders flinch: insuring hyperscaler bonds costs more than it ever has. When Nvidia offers to backstop its best customer so that customer can keep ordering Nvidia chips, the balloon is inflating itself, and looks magnificent right up to the moment it doesn't.
Beijing supplied the pin. CXMT, the state's memory champion, listed and multiplied several times over before the closing bell, a giant's valuation conjured in an afternoon, while homegrown lithography tools began chewing at ASML's franchise. Every export ban Washington signed turned out to be a syllabus. The stories rhyme: interceptor stocks, hyperscaler spreads, listing proceeds. The side that refills cheapest stays in the fight.
Tankers Sailing Dark
Oil gives the game away. Futures fell hard on the strike pause; the physical market shrugged. Dated Brent still trades in steep backwardation, refined products hardly moved, and only eight commodity vessels transited Hormuz on Sunday. Saudi cargoes take the long way round Africa and tankers out of Yanbu sail dark. Screen traders relaxed. The people who own hulls and write the insurance did not.
The same gap runs through the AI books. The largest spenders are pouring vast sums into plant and chips, yet only a fraction reaches this year's income statements as depreciation; the remainder waits on the balance sheet, flattering profit while cash leaves the building. If the silicon ages faster than the books assume, the deferred charge arrives early and heavy. So the valuation quarrel, record-sized world equities for the bears, a Nasdaq below its own decade average for the bulls, collapses into whether the profits are real.
Renting the Nap
Stock correlation has dropped to record lows, so single names lurch about while the index barely stirs; uncorrelated noise adds up to a placid S&P, whose volatility is priced too cheaply. The letter's structure exploits that mismatch: it collects decay from the summer lull through near-dated options while holding later-dated ones that come alive if the tape wakes. It rents the nap and owns the alarm clock.
The later leg sits inside the pre-election window on purpose. Midterm years tend to grind sideways from August into the vote and loosen only afterward, and the ballot is roughly a hundred days out. Affordability now writes policy: Mexican cattle imports reopen in late August to lean on beef prices, a margin lifeline for Tyson and JBS, while healthcare, crypto rules and residential solar get kicked around as footballs into November. Chop is the base case, and the trade is shaped to collect while enduring it.
A Gauntlet in Thin Water
The calendar offers no shelter. It opens with a hefty Treasury auction, Wednesday sets the Fed decision beside Microsoft and Meta reporting after the close, Thursday piles up the initial estimate of quarterly GDP, core PCE, the Bank of England and then Apple and Amazon, and Friday closes out with the Bank of Japan, eurozone inflation and China's PMIs. Thin summer liquidity turns each landing into a louder thud.
The Fed is the odd item. Futures give a hike about a one-in-three chance, and under Warsh the blackout leaks have dried up; whichever way the vote lands, much of the market gets it wrong. My base case is a hawkish hold, a dissent or more, and a press conference engineered to reveal nothing. I will be reading the dissent count and the shape of the Brent curve before the index level. The quartermasters have spoken. The generals have not.
Get the next Tuesday Target free
One real options trade every Tuesday before the US open, entry, stop and target named. Free to read.