US Natural Gas (UNG): Widow Maker Meets Stealth Liquidity
Why a stealth repo backstop, rising yields and cheap implied volatility make US natural gas (UNG) a mean-reversion setup worth understanding.
What came of it
I closed this trade on 30 December 2025, after 26 days, at -33% on the capital at risk.
The Dumb Money Read the Plumbing
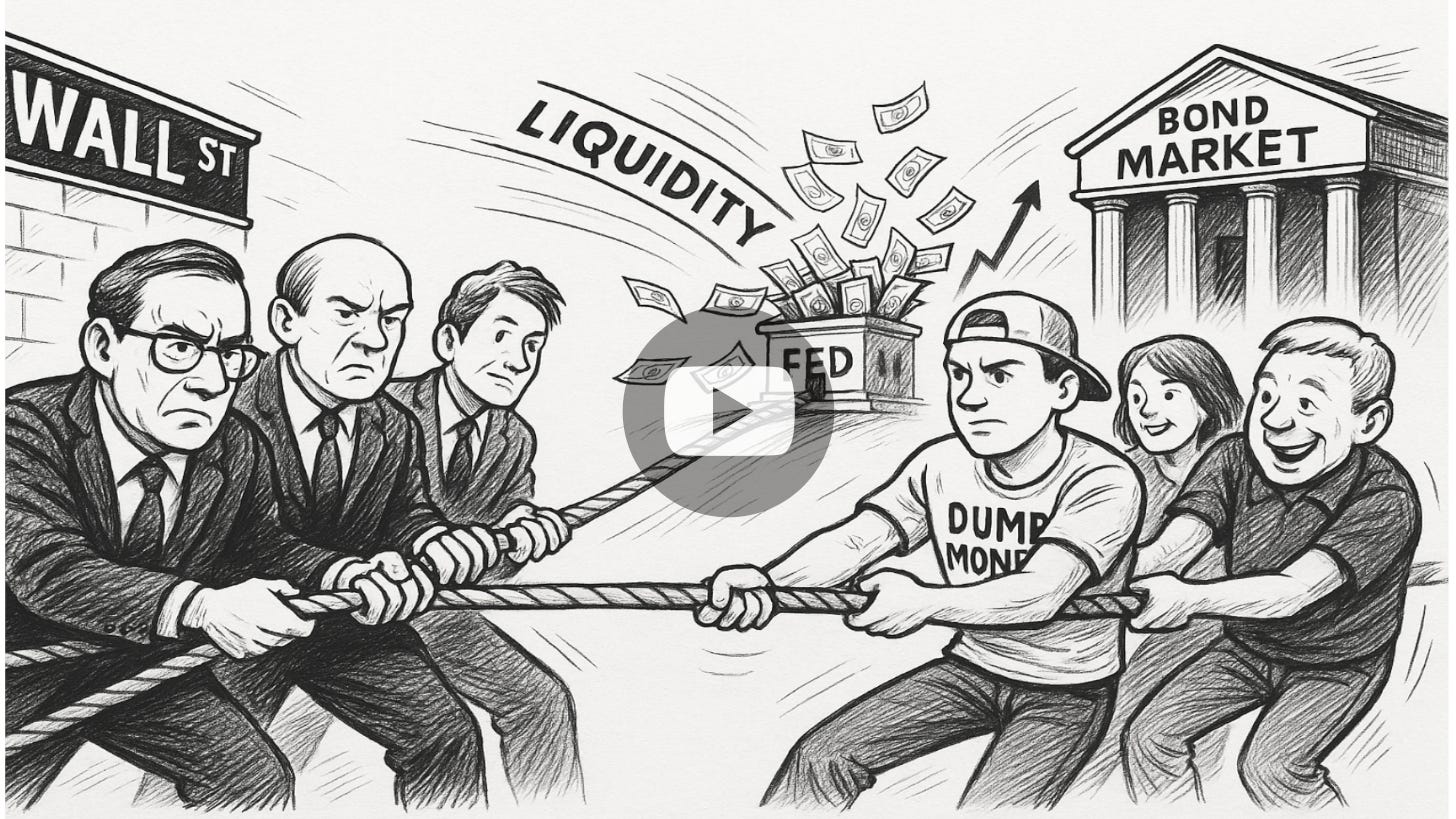
The professionals had a rough year. They built models, bought protection against catastrophes that mostly declined to show up, and watched the retail crowd walk past them by doing the least clever thing imaginable: buying every dip. Knowing a lot about tail risk becomes a handicap when the tail keeps getting clipped by a central bank that cannot bear a stressed funding market. Retail skipped the models and kept the single insight that matters: liquidity gets forced into the system whatever the macro weather does.
The pretext hides in the repo market. Everyone is fixated on the rate decision on Wednesday while the Fed prepares something more consequential: a recurring monthly purchase, likely around $45 billion, dressed up as reserve management so nobody has to say the letters QE out loud. Cash enters the pipes on a schedule and equities float on it, which is the plainest explanation on offer for a stock market that keeps ignoring its own fundamentals.
The bond market has declined to join the performance. Yields are climbing, tightening conditions at the exact moment the Fed wants them looser. Picture a driver flooring the accelerator while the passenger stamps on the brake: the engine screams, the cabin smells of hot rubber, and eventually a part gives way. That friction sets the tone for everything else in the letter.
Copper, Coal and the Refinery Bottleneck
Underneath the liquidity story, capital is voting with its feet. Investors betting on a run-it-hot economy are leaving bonds for things you can drop on your foot. Fiscal excess plus tariffs makes for inflationary growth, and copper and energy have started trading the way gold does when paper promises look thin. Big Tech has stopped pretending its capital spending is about returns; chips and data centers get bought because falling behind in AI reads as extinction, so the floor under hardware demand survives any rate path. Further out, the West is buying mines while China keeps the refineries that turn ore into batteries, so owning the dirt settles nothing, and India's coal build-out stretching to 2047 says the Global South has picked security over climate timelines. Traditional energy carries a tailwind no press conference can cancel.
The Widow Maker Rolls Uphill
Which brings me to natural gas. The futures curve sits in mild backwardation, so each monthly roll hands UNG a small lift rather than the usual tax. Gas also behaves like the old friend who vanishes for months and then turns up on your doorstep, and I am content to lean on that mean-reversion habit with a modestly bullish structure whose worst case is fixed in advance. Storage is comfortable. The base case has winter weather, LNG and geopolitics delivering their usual chaos inside a normal band, with a genuine headline possible but statistically rare.
For an options trader the interest sits in the wings. Implied volatility across the wider tape has sagged to complacent levels, yet in gas the far strikes still cost real money because gas has a reputation to uphold. Fighting the seasonal liquidity flood, with systematic funds re-levering and buybacks at peak flow, is expensive, so cheap index protection covers the bond tantrum while in UNG the edge lies in fading overpriced tails with risk capped on both sides, managed actively if price runs at either short strike. This remains the widow maker. Anyone who prefers a quiet life has my blessing to skip it.
Wednesday, JOLTS and the Yield Vote
The docket is crowded: the Fed on Wednesday with a cut priced against hawkish muttering, the RBA, Bank of Canada and SNB adding noise, JOLTS testing labor resilience, and Oracle and Broadcom reporting into an AI complex priced for perfection. I care less about the headline decision than about what yields do after it. If the bond market keeps voting no while the Fed pumps, the tantrum insurance earns its keep. If yields settle, the liquidity tide does the lifting and the widow maker drifts back toward where it belongs. The interesting action stays in the plumbing, and plumbing rarely makes the front page.
This page is the write-up. The full letter, with the trade and its exit rule, is on Substack.
- UNG
Get the next Tuesday Target free
One options trade. Every Tuesday. Scored in public. The exit rule is on the card, and the letter is free to read.