China Internet (KWEB): The Floor Holds Until Tokyo Speaks
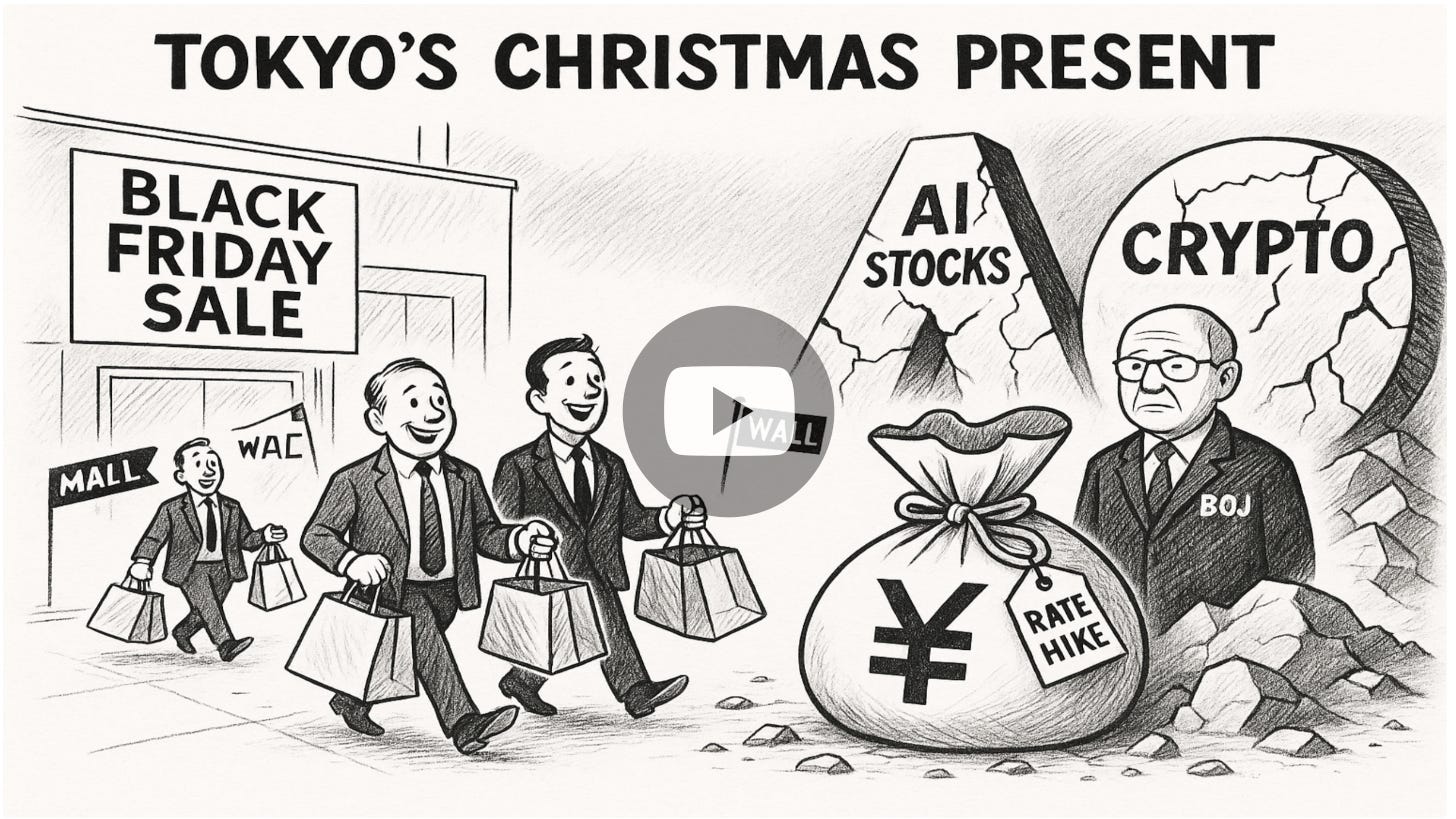
Why a Bank of Japan hike before Christmas outranks Black Friday records, and how a half-size KWEB put spread respects a floor built by flows.
Tokyo Wraps a Rate Hike
The letter starts where the noise is, at the mall, and walks away from it. Black Friday posted nominal records and the commentary took that as proof of a sturdy shopper. Adjust for prices and the volume story thins out fast. What remains is the K-shaped economy: a wealthy leg buying AI stocks and a wider leg putting groceries on credit. Neither leg is the part that worries me.
The worry sits in Tokyo. The Bank of Japan is telegraphing a rate hike in the days before Christmas, and cheap yen has funded a great deal of global speculation for years. Nobody circulates a memo when that funding gets dearer; you learn it from what snaps first. Shanghai silver inventories have been emptied and the price has run to records, while Bitcoin and the equities that borrowed their nerve from crypto have come apart as easy money drains out. The claim I would underline: when the liquidity tide recedes, scarce things you can hold have a habit of outlasting digital promises.
The State Put Stops Answering
A side story rhymes with the main theme. Life insurers have piled into private equity and private credit, assets that pay a nicer yield on paper and cannot be sold in a hurry, and that slice of their books is now larger than it was going into the last crisis. Illiquidity dressed up as yield is yen-funded speculation wearing a suit.
The other side story matters more for KWEB. China Vanke, a state-backed developer everyone had filed under safe, is asking bondholders to wait for their money, and the belief that Beijing rescues every well-behaved builder is being retired in public. A directional lean on China internet sits next to that fact, and the letter lets the position size do the reconciling rather than pretending they are unrelated.
Half Size, Exit Written First
The trade is a put credit spread on KWEB, the bull put flavour, chosen because the probabilities and the payoff shape looked favourable for a directional bet. The position runs at half the usual size because the structure departs from the letter's normal approach. And the exit is drafted before the entry: if KWEB moves against the spread, the plan is to roll into the following month and add a call credit spread on the other side, converting a directional lean into an iron condor that gets paid for a range.
Why the caution when volatility looks sedated? Because the calm has mechanical causes with expiry dates. A large corporate buyback bid runs until December 19, and dealers are long gamma, so their hedging leans against every move and flattens the tape. That is a floor built by flows, and flows change. The cushion that damps a selloff caps a rally too, and once it fades or flips, the drop beneath it is genuine. The letter's tactical read, early December as a choppy waiting room and the artificial floor as a spot to build quality exposure through capital-efficient call spreads, shares the temperament of a half-size put spread with a condor as fallback. It also concedes, given its ordinary record on directional calls, that the opposite side is a respectable place to stand.
Blackout, Then the Chair, Then Tokyo
The Fed is inside its blackout window, so the spoken version of the Fed put is switched off, which leaves room for Trump to name his pick for the next Chair, a reveal the letter ranks above any data release for its power to jolt bonds. ISM Services tells you whether the manufacturing slump has crossed into the wider economy, and Friday's PCE report puts the "inflation is dead" narrative under the lamp. On earnings, CrowdStrike and Marvell answer the question the AI trade keeps dodging: whether the spending is reaching software revenue or staying parked in hardware capex.
Then the calendar hands back to Tokyo. A BoJ hike lands in the thin days before Christmas, the buyback bid switches off shortly before it, and the gamma cushion was never permanent. Read those together and the deceptive calm has a shape: a floor that holds right up until the people holding it leave for the holidays.
This page is the write-up. The full letter, with the trade and its exit rule, is on Substack.
Get the next Tuesday Target free
One options trade. Every Tuesday. Scored in public. The exit rule is on the card, and the letter is free to read.