China Internet (KWEB): Whoever Sprays Hardest Owns the Tape
Why US liquidity is tightening under soft Fed talk while China floods its tape, and what that gap means for options on KWEB.
Champagne Upstairs, Valves Closing Below
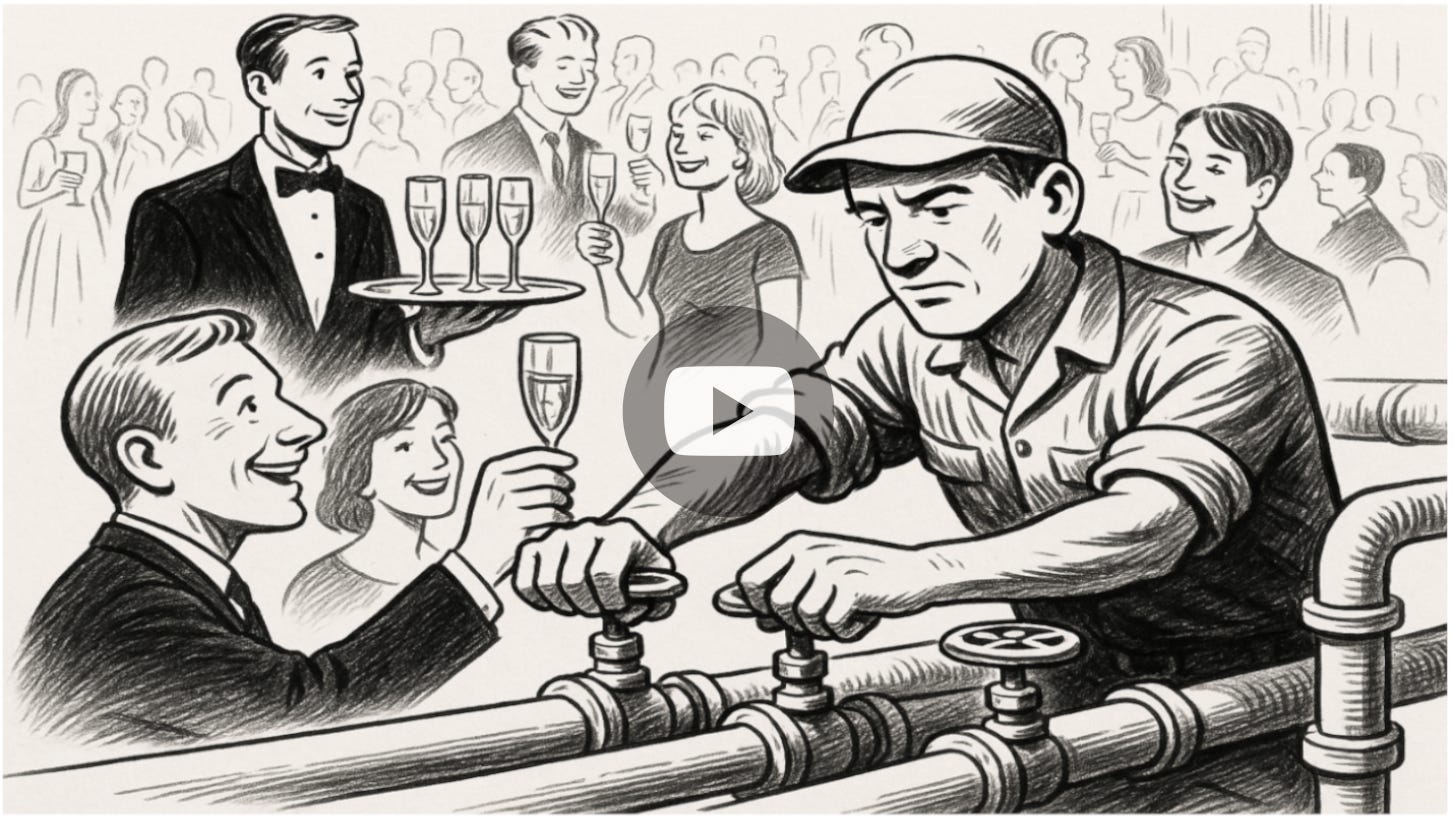
The letter opens on a picture I keep returning to: a party on the upper deck toasting rate cuts while someone below the waterline quietly shuts the valves. The Fed's spare-cash bucket, the reverse-repo facility that soaked up excess and handed it back on demand, sits close to empty. Treasury is rebuilding its own account, which pulls dollars out of circulation until it spends them again. Balance-sheet reduction grinds on without making headlines. Softer speeches, tighter pipes.
Why does that outrank the next dot on the calendar? Because the reflex that caught every dip for years ran on flow more than conviction: passive inflows arriving on schedule, dealers hedging into weakness, a deep pool of cash willing to fill any gap. Slow the hoses and the wobble that once lasted an afternoon becomes a question about who is positioned where. A smaller shock does more damage, and that arithmetic sits underneath everything else in the issue.
Discipline Talk, Liquidity Spray
Here is the irony the letter enjoys most. Washington talks easy and drains; China talks discipline and floods. China's internet names are punching through ceilings that held for a decade while American macro data wheezes along. The letter calls it policy-assisted optimism, and the ingredients are familiar: fresh liquidity, margin accounts stirring after a long sleep, and an AI chip champion for the crowd to gather behind. None of that depends on the underlying businesses improving. Money looking for a home and a story to justify the address will do.
The phrase the letter lands on, the wettest tap wins, is a claim about relative liquidity rather than relative virtue. Whoever sprays hardest gets the tape, at least until the tap turns. That strips the moral debate out of the China question and leaves a plumbing question, which is the only version I find tradeable.
Less Force to Move Prices
For anyone running options, the useful shift is in what a dip means. When liquidity was abundant, a sharp down day in KWEB or anywhere else was a gift to premium sellers because the bounce arrived on cue. With the cushion gone, the same down day carries information about positioning, and the bounce has to come from someone with actual cash. That tilts the odds toward long convexity where the tap is wet and against short premium where it is dry.
The letter's structure follows from that. It frames the China view as a defined-risk directional bet, a call debit spread, with the maturity chosen so time decay and any softening in implied volatility do not eat the thesis before it plays out. Then the sting in the postscript: the letter says we aren't taking the trade and flags the idea as a possible contra signal. A view can be right about the plumbing and still be crowded at the door. Reading a trade idea next to my own reluctance to hold it is the more instructive part of the exercise.
Tariffs, Underwriters and the Mittelstand
The rest of the issue lists pressures building before the official numbers notice. The 40% levy on transshipped goods, plus the end of the de minimis loophole, hits margins first; buyers squeeze suppliers, firms absorb what they can, and shelf prices restructure over quarters. Margin commentary on earnings calls will tell that story well before the inflation release does. Around Ust-Luga, the drone strike and the pipeline and refinery noise nudged crude, yet the telling number sits in marine war-risk premiums, which underwriters move the moment a route looks fragile.
Germany rounds it out: real-time VAT and payroll data show smaller firms shrinking on revenue and headcount, with construction and hospitality weakest and investment scarce, while European indices break higher regardless. Whether mean-reversion and early capex signs hold is the thing to check against the next batch of that data. Behind all of it sit the gauges on the tap itself: the reverse-repo balance, the pace of Treasury's refill, margin balances in China. When one of them turns, the tape tends to follow.
This page is the write-up. The full letter, with the trade and its exit rule, is on Substack.
Get the next Tuesday Target free
One options trade. Every Tuesday. Scored in public. The exit rule is on the card, and the letter is free to read.