Materials (XLB): A Raised Floor and a Sector Bumping Its Head
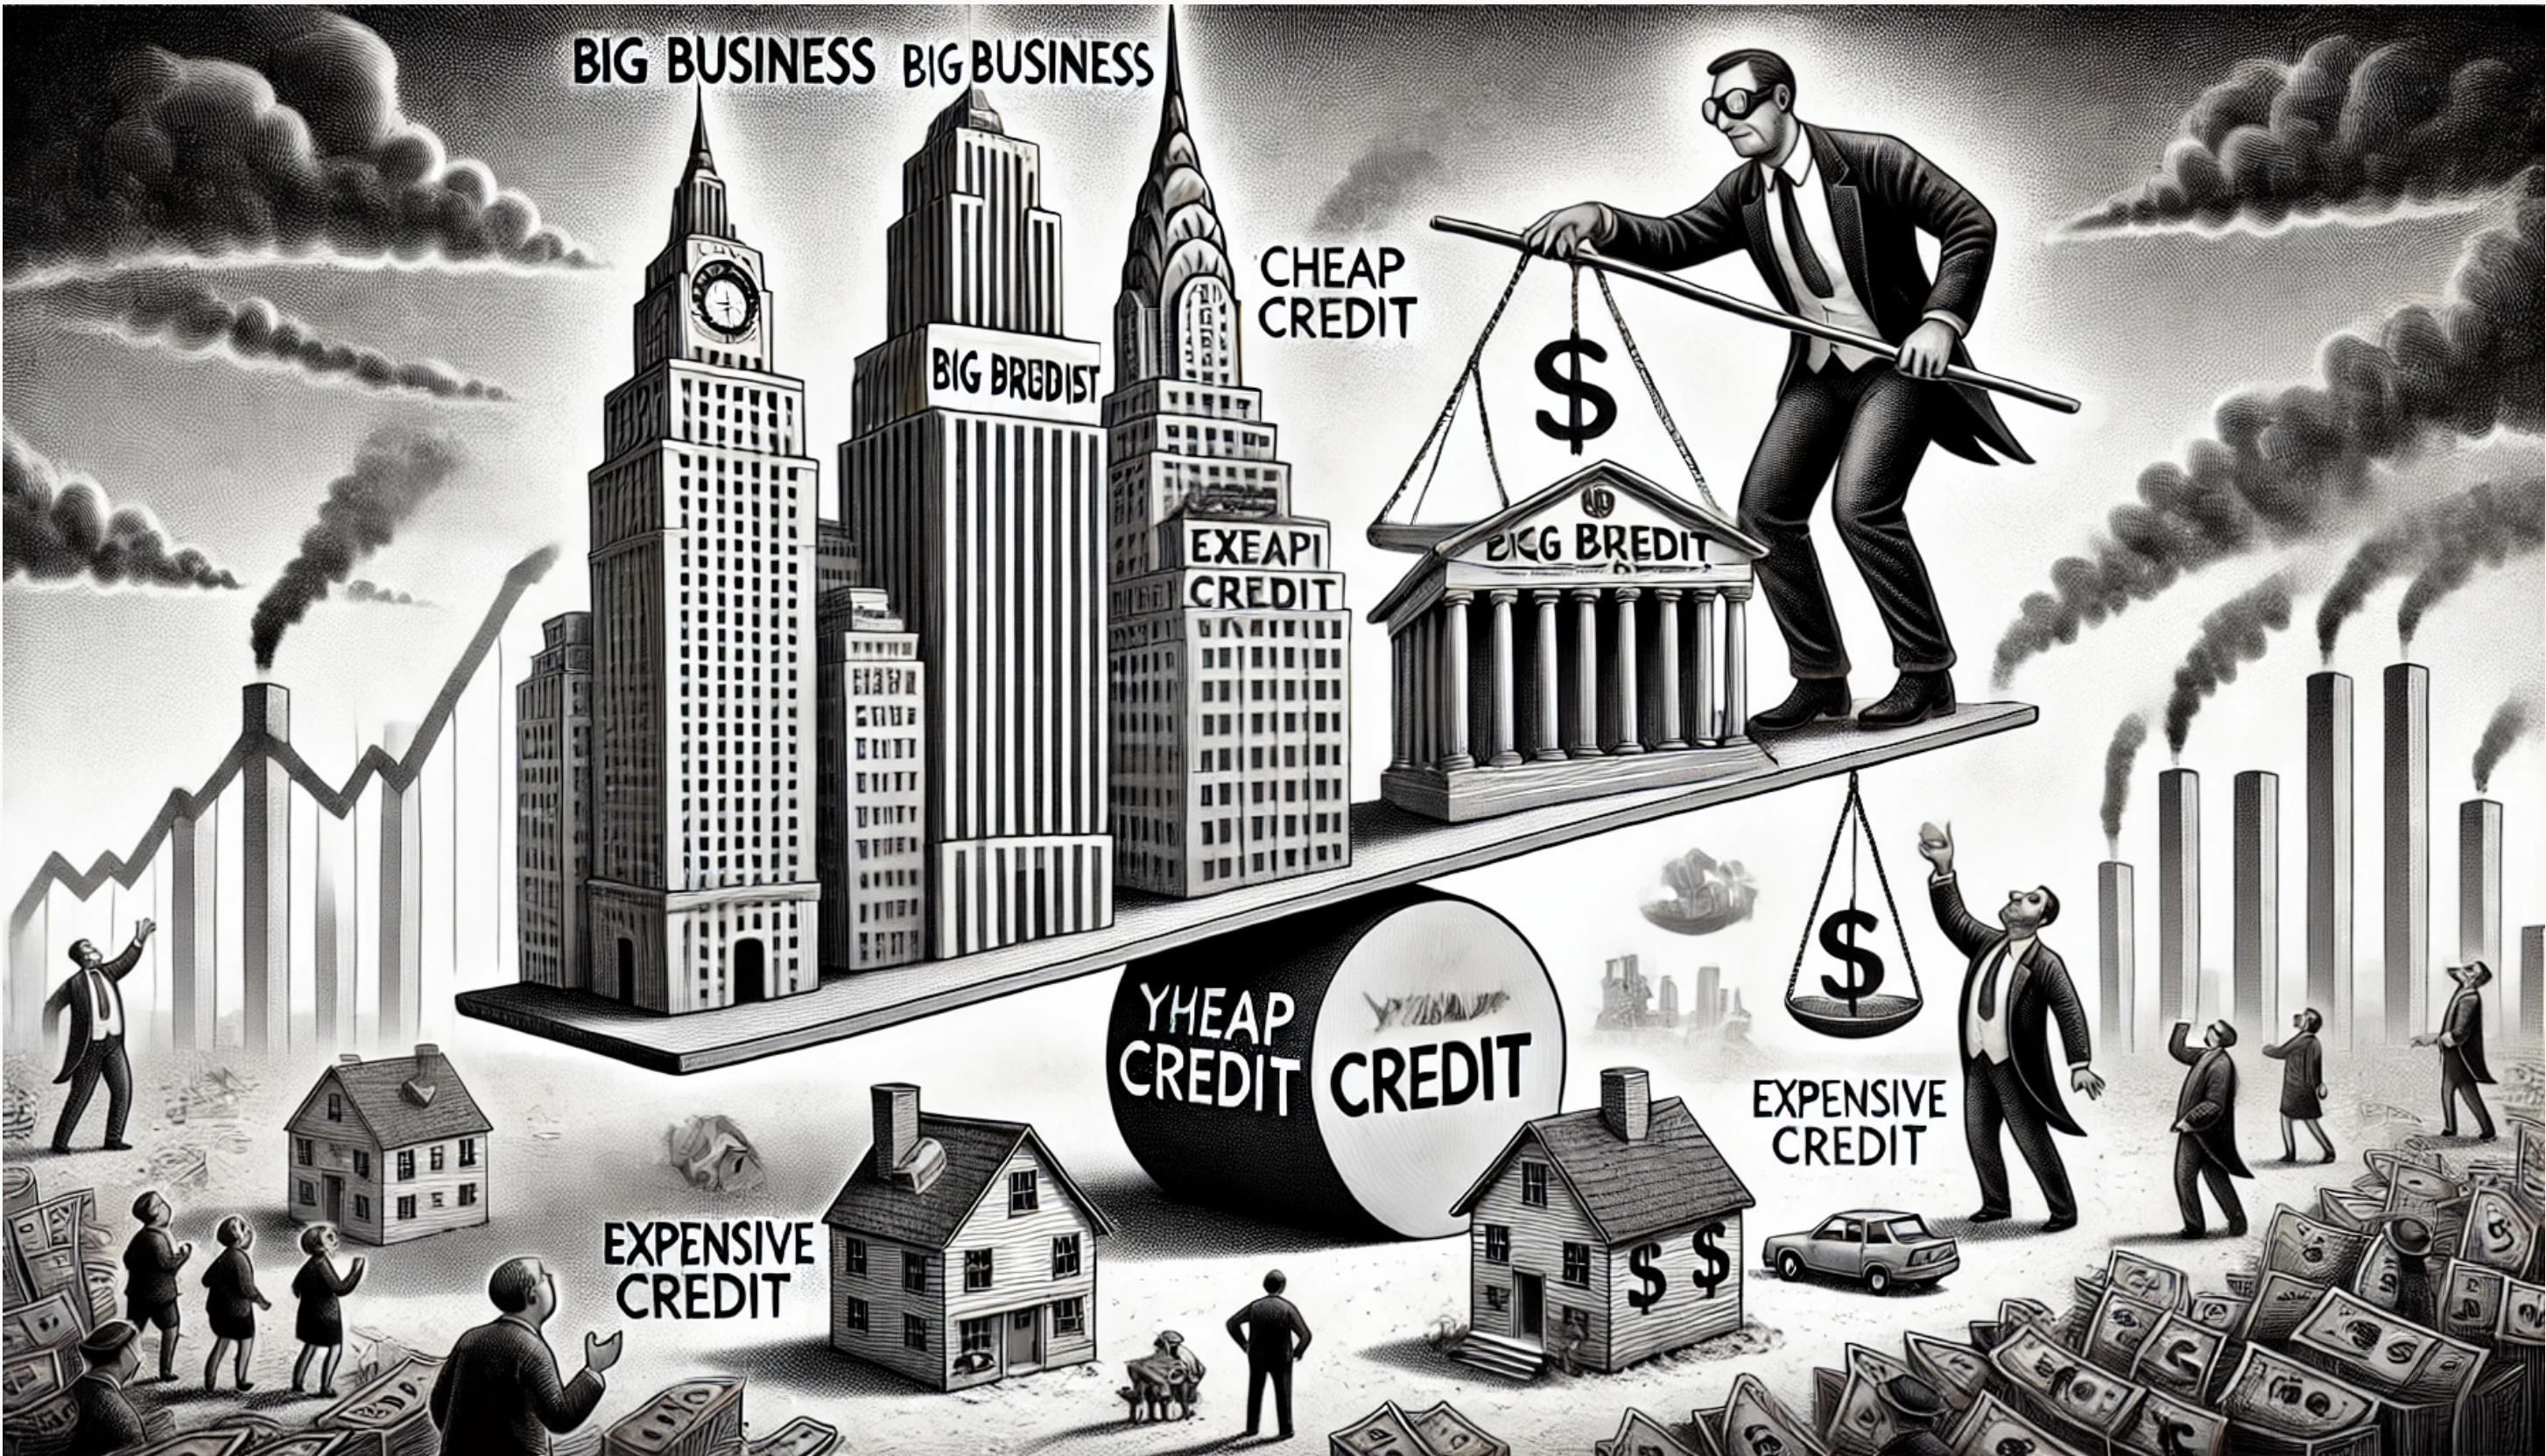
Why a Treasury-engineered flat curve props up index calm while Materials stall, and how that shapes a defined-risk options view on XLB.
Ceiling Fixed, Floor Rising
A house whose floor keeps rising toward a fixed ceiling looks perfectly stable right up until nobody can stand in it. That is roughly the architecture Scott Bessent has chosen for the Treasury market. Rather than let long-dated yields find their own level, he is tilting new issuance toward the short end and starving the long end of supply. Fewer long bonds to absorb means a lid on the long yield, the curve flattens, and the pundits call it pro-growth.
I call it a transfer. Cheaper long-term borrowing lands in the laps of large, well-rated corporations, the same mega-caps that already set the tone of every index. They roll cheap debt and their valuations get a goose. Smaller firms, riskier borrowers, the people who actually hire, keep facing expensive or rationed credit. Regional banks watch their net interest margins get squeezed between a pinned long end and a stubborn short end. None of that appears in the wealth effect the herd is busy celebrating.
The Parlor Trick's Audience
The trick only works while the audience is willing to be fooled, and the audience is split. At the bottom, Goldman's lower-income dashboard is a mess of contradictions: fewer jobs but rising wages, thinner traffic on the value menu at McDonald's while discount retailers stay crowded, more credit drawn and savings sitting low. Read together it describes a consumer who is stretched, which is the condition that tends to come just before broke. A broad retail rebound has a hard time starting from there.
At the top, the picture is oddly brighter. After a nasty stretch for luxury, and a particularly nasty one in China, Gucci has reported something that looks like a floor. The figures remain weak, but the big spenders are drifting back and a few marquee names beat expectations. If Chinese demand recovers and Western discretionary budgets hold, luxury could turn into the one surprise on the upside. The flat curve flatters the wealthy end of the room and leaves the rest paying for the tickets.
Materials Bumping Their Head
Here is where the curve engineering meets a sector chart. Materials have run into resistance, the sort of level where a group stops rising and starts arguing with itself. When liquidity is being poured into the largest balance sheets and the real economy is told to wait, a cyclical, input-heavy sector without mega-cap tailwinds has little reason to break out cleanly. It also has little reason to collapse while the index is being kept dancing. A ceiling overhead and a floor propped underneath describes a range.
For an options trader a range is an argument for defined risk on both sides with a lean toward the more likely disappointment. The letter frames the XLB idea as a condor tilted slightly bearish, premium collected from a sector that looks fairly priced at best and probably a touch rich. The tilt matters: neutrality would pretend the curve trick has no losers, and I have just spent a page saying it does. The mechanics stay in the letter where they belong.
Sniffing Out the Stink Early
Illusions fail when something real refuses to cooperate, so the watch list is about the real. First the CPI print. After months of everyone agreeing inflation was handled, energy and sticky services, shelter above all, have put a hotter reading back on the table. Option-implied volatility has climbed back toward where it sat last year, which tells you the market has remembered that disinflation can stall. A hot number would test how firmly the long end stays pinned when issuance alone is doing the pinning.
Then the credit plumbing: regional bank margins and the quality of lower-quartile borrowing, since that is where the raised floor bites first. And the sector itself, whether Materials respect the level they keep knocking against or push through it. A curve can be flattened by decree for a while. The smell arrives before the collapse, and the job is to notice it while the market is still applauding.
- XLB
- Iron Condor
What came of it
I closed this trade on 7 March 2025, after 28 days, at +50% on the capital at risk.
Get the next Tuesday Target free
One options trade. Every Tuesday. Scored in public. The exit rule is on the card, and the letter is free to read.