Salesforce (CRM): Record Software Shorts Meet a Fed Faking Calm
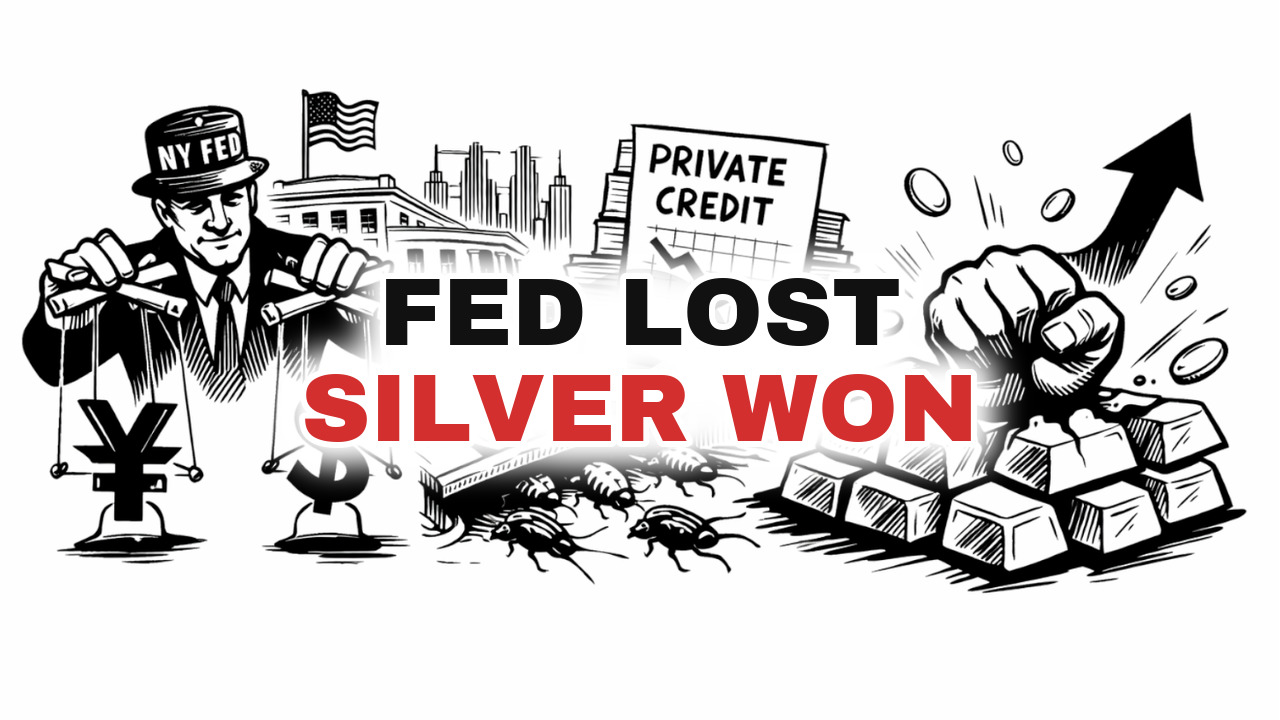
Why a Fed rate check, a private credit markdown and a silver squeeze turn record hedge fund shorts in software into a coiled spring for Salesforce.
Breaking What They Cannot Print
The letter opens with a rate check. The New York Fed calling dealers to ask about dollar-yen levels is the polite name for a warning shot, and the letter reads it as a Plaza Accord conducted without the ceremony: Washington lending its currency to hold up a strategic ally in Tokyo. Once the dollar becomes an instrument of alliance management, its price stops telling you about the economy and starts telling you what the authorities can tolerate.
The second crack is uglier. A BlackRock private credit fund marked its assets down by nearly a fifth, which is what happens when loans valued by spreadsheet meet a rate environment that refuses to cooperate. The smooth charts private credit sold were smooth because nobody ever asked for a bid; a model had already supplied the price. Higher rates are the flashlight, and the letter's cockroaches are scuttling out from under the floorboards of private equity.
Put those together and the silver squeeze stops looking like an accident. Capital is walking away from managed currencies and opaque credit marks toward things with a physical price, metal that has to be delivered by someone who actually owns it. When stability is faked, the market goes looking for the items nobody can print and breaks them upward.
Fading the Clowns
This is where Salesforce enters. Hedge funds are as long semiconductors as they have ever been and as short software as the record allows. The letter calls this a coiled spring, and the mechanics are simple: a boat with everyone on the same side tips under a passenger shifting weight, no storm required. A modest earnings beat in software, or a stumble in chips, is that passenger.
Salesforce is the letter's chosen way to lean against that crowd. Expectations for software heading into earnings have rarely been lower, so the bar a company has to clear is lying on the floor. The letter frames this as food for thought and stops short of a formal entry, and I would add that fading a consensus this lopsided is a bet on positioning, on the crowd being forced to move, far more than a view on the company's product roadmap.
Protection at a Fake Discount
For an options trader the letter changes how implied volatility reads. Asset managers hold record short-volatility positions, so the option prices on the screen are being subsidised by people who need calm to keep their books alive. Cheap protection is a gift from a crowd that cannot afford a spike. The letter's tactics section pairs taking that gift with exposure to the tangible economy: gold, silver and the domestic industrials it files under a Long Detroit label, set against the financialised Davos consensus.
On the Salesforce idea, the note about maturity carries weight. Squeezes are events of timing, and timing is the thing a positioning thesis cannot promise. A longer maturity is a way of paying for patience: the crowd may need a quarter to be forced out when the thesis assumed a week, and contracts that expire before the argument resolves are a donation to the other side.
Subpoenas, Earnings and Tokyo Inflation
The calendar the letter lays out is dense. Wednesday's FOMC is the centrepiece, with Powell fielding questions about political subpoenas alongside the awkward matter of currency intervention. A chairman explaining why his trading desk was checking yen quotes is a chairman on unfamiliar ground, and unfamiliar ground is where guidance goes wrong.
The same window holds results from Microsoft, Meta, Tesla and Apple, premiums that demand validation every quarter and get less forgiving each time. Friday adds US producer prices and a Tokyo CPI print the letter flags as capable of breaking the JGB market, which after the rate check loops straight back to the dollar. For the software thesis the tells are narrower: a semiconductor darling stalling, or a software name clearing its low bar with room to spare. Either would set the spring loose. Until then the crowd is short, the metal is rallying, and the people who wanted stability are the ones making the tape fragile.
This page is the write-up. The full letter, with the trade and its exit rule, is on Substack.
- CRM
- Hedges
Get the next Tuesday Target free
One options trade. Every Tuesday. Scored in public. The exit rule is on the card, and the letter is free to read.